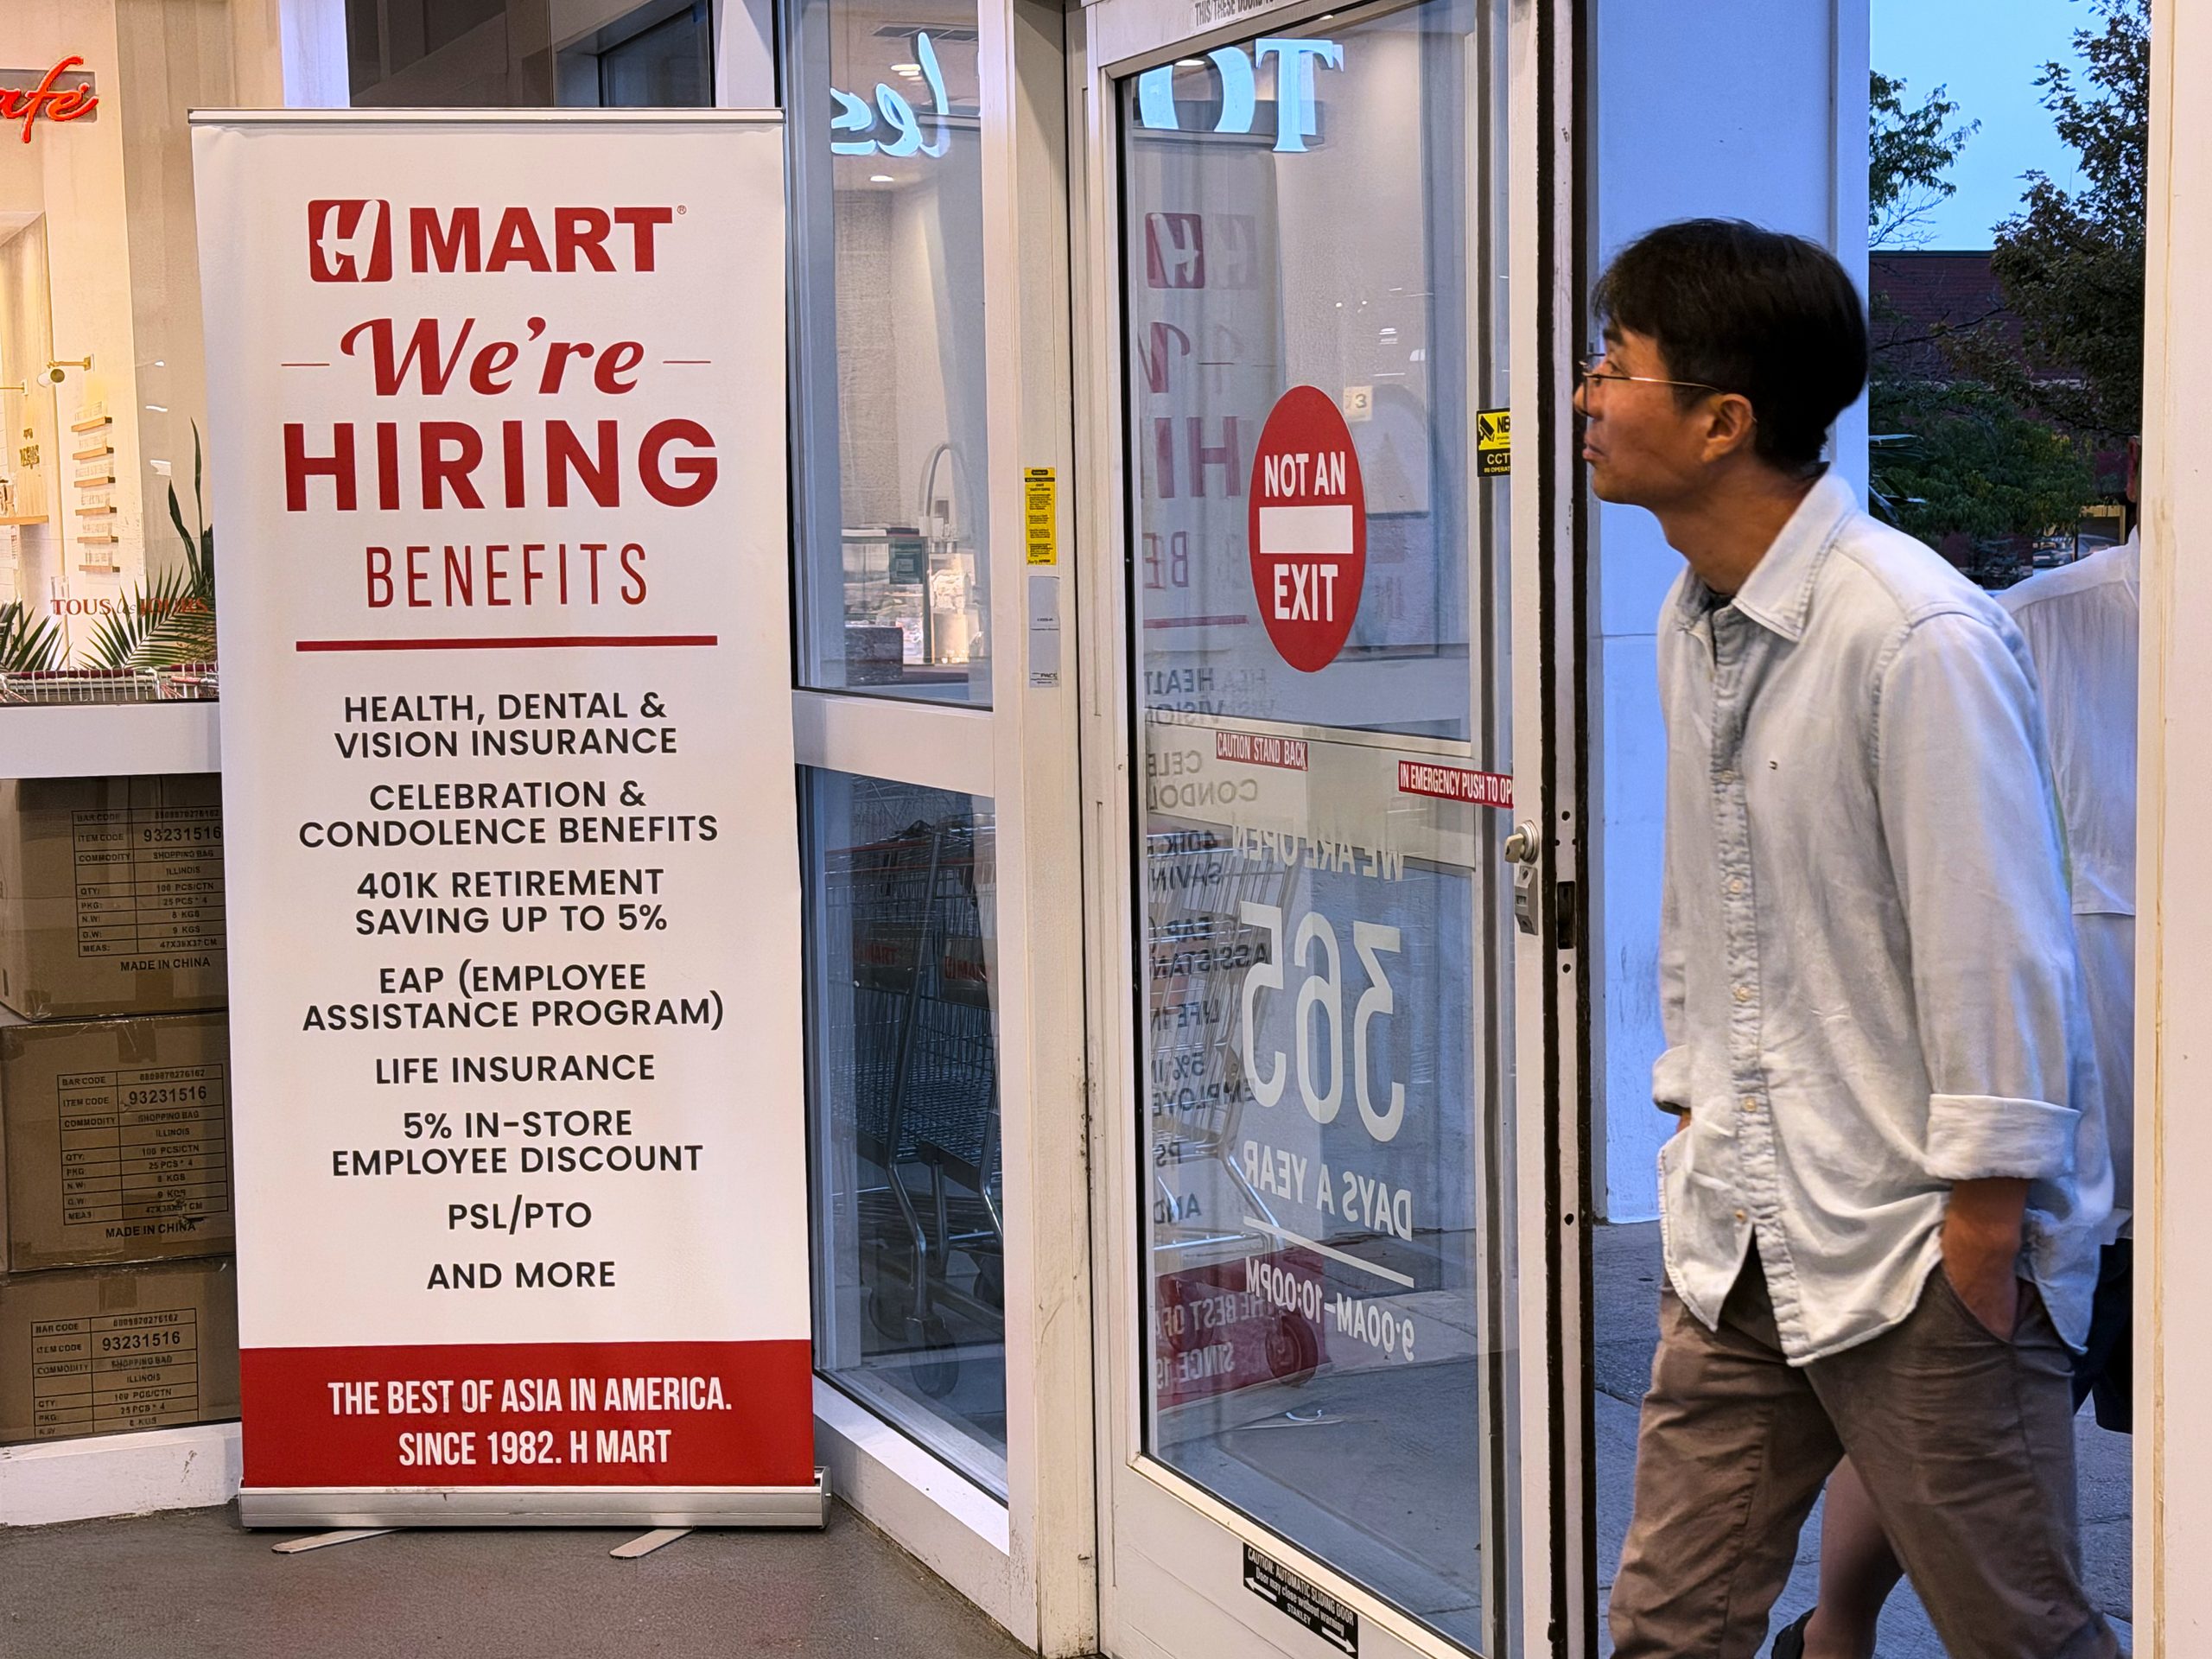
New applications for U.S. unemployment benefits fell to 197,000 last week, keeping layoffs near levels rarely seen in modern labor-market data and strengthening the case that employers remain reluctant to cut workers even as hiring has cooled.
Initial claims declined by 1,000 in the week ended Sept. 19 from a revised 198,000 the week before, according to the Labor Department. Economists surveyed by Reuters had expected 201,000 claims. The four-week moving average, which reduces some of the volatility in the weekly figures, dropped by 1,750 to 202,250. Claims are now hovering around levels last seen in the late 1960s.
The report adds to evidence that the labor market is avoiding the kind of broad layoffs that would normally accompany a sharp economic slowdown. It does not, however, point to a return of aggressive hiring. Instead, the latest data fit an increasingly unusual pattern in which companies are holding onto existing employees while remaining cautious about expanding payrolls.
Low Layoffs Are Masking a Much Cooler Hiring Market
August payrolls rose by 162,000, a substantial improvement from the weak readings earlier in the summer, but the three-month average job gain was only 71,000. The unemployment rate held at 4.1%, while June and July payroll growth was revised to 31,000 and 21,000, respectively. Those figures leave the labor market stable but considerably less dynamic than during the post-pandemic hiring boom.
The same pattern appears in the Bureau of Labor Statistics’ job-openings data. Employers had 7.3 million openings in July, while hires were little changed at 5.1 million. Layoffs and discharges totaled 1.7 million, with the layoff rate holding at just 1.0%. Quits were also subdued at 3.1 million, another indication that workers are not moving between employers as freely as they did when labor demand was stronger.
Continuing unemployment claims provide another encouraging signal. The number of people receiving benefits after an initial week of aid rose only slightly to 1.719 million in the week ended Sept. 12, leaving the total near its lowest level since May 2023. That suggests the claims data are not simply reflecting fewer new layoffs; the overall number of workers remaining on unemployment insurance has also been moving lower.
Weekly claims can be noisy, particularly around holidays. Economists have pointed to seasonal-adjustment complications surrounding Labor Day and residual seasonal patterns that can push claims lower late in the year. Still, the decline in the four-week average makes the latest reading harder to dismiss as a one-week distortion.
Fed Has More Room to Focus on Inflation
The strength in claims is especially important because the Federal Reserve has shifted toward a more restrictive policy stance. The central bank raised its benchmark rate by a quarter percentage point on Sept. 16 to a range of 3.75% to 4.00%, citing elevated inflation while describing economic activity as expanding at a solid pace and employment conditions as relatively stable.
With layoffs remaining scarce, policymakers face less immediate pressure to support the labor market by holding rates down. The Fed’s latest projections put the median year-end federal funds rate at 4.1%, broadly consistent with the possibility of another quarter-point increase if inflation and economic activity remain firm. The claims report alone will not determine that decision, but it removes one potential argument against further tightening: evidence of a sudden deterioration in employment.
Markets were already leaning in that direction Thursday. Treasury yields climbed and the dollar reached a two-month high as investors responded to a combination of resilient economic data, inflation concerns and hawkish comments from Fed officials. The 30-year Treasury yield briefly moved above 5.45%, its highest level since 2004, while traders increased expectations that the Fed could raise rates again before year-end. The jobless-claims report contributed to that backdrop, although it was not the only force moving rates.
For investors, the distinction between low layoffs and strong hiring remains important. A labor market in which businesses retain employees but add relatively few new ones can keep unemployment contained and consumer income supported without producing the rapid payroll expansion associated with an overheating economy. The risk for markets is that persistent job stability, combined with firm activity and renewed inflation pressure, gives the Fed more latitude to keep borrowing costs elevated.
The next tests arrive quickly. August job-openings and labor-turnover data are scheduled for Sept. 29, followed by the September employment report on Oct. 2. A continued combination of low layoffs, stable unemployment and firmer hiring would reinforce the Fed’s case for keeping policy restrictive, while a renewed slowdown in payroll growth would show that the low claims numbers are concealing a labor market that remains difficult for workers trying to find new jobs.