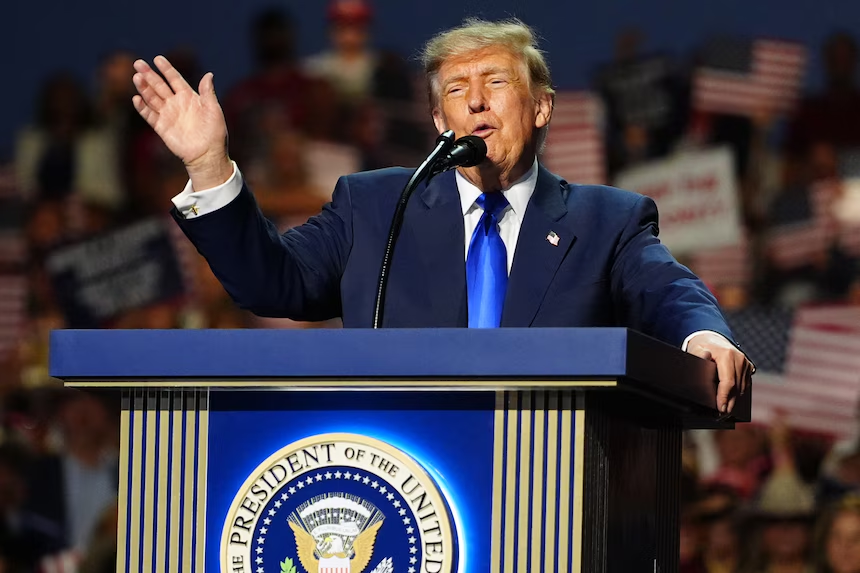
President Donald Trump says Americans may have to wait until after the November 3 midterm elections for meaningful relief from elevated oil and gasoline prices, tying his forecast to an expectation that the war with Iran will ease once the election is over.
The prediction is arriving as the energy shock is moving in the opposite direction.
Brent crude surged more than 6% Thursday to around $107 a barrel, while U.S. West Texas Intermediate climbed above $101. The national average for regular gasoline reached $4.277 a gallon, according to AAA, up from $4.14 a week earlier and $3.19 a year ago. Diesel reached a record $5.977 per gallon.
California remains considerably more expensive. AAA put the state’s regular gasoline average at about $5.90 Thursday, while diesel was approaching $7.91 a gallon.
Trump acknowledged Wednesday that lower fuel prices may not arrive before voters go to the polls.
“Right after the election, oil prices are going to be tumbling downward,” Trump told reporters before traveling to Dallas for a Republican midterm convention. He added that he expected the decline to take “a little bit longer than the midterm.”
Trump’s timeline is a prediction rather than an established market forecast. Oil prices are determined by global production, shipping availability, inventories, demand, refinery capacity and geopolitical conditions, and there is no mechanism that would cause prices to fall automatically because the U.S. election has concluded.
For investors, the more immediate question is whether the conflict disrupting Middle Eastern energy supplies begins to ease — and how much inflation pressure accumulates before that happens.
Trump Expects the Iran War to Ease After the Election
Trump linked his oil-price forecast directly to the war with Iran.
He asserted that Iran is trying to prolong the conflict in an effort to influence the U.S. election and said he believes Tehran will eventually relent after November 3.
“I think the war’s going to end immediately after the election because they can’t hold out any longer,” Trump said. His assertion about Iran’s electoral motives has not been independently established.
The conflict is now in its seventh month.
Trump initially said the war would last a matter of weeks after U.S. and Israeli forces attacked Iran in late February. Fighting has instead continued through the summer and into September, disrupting one of the world’s most important energy corridors.
Before the conflict, roughly 20% of global petroleum passed through the Strait of Hormuz. Oil traffic through the area has since slowed significantly, while attacks involving tankers and energy infrastructure have repeatedly pushed risk premiums higher across crude and refined-fuel markets.
Recent fighting has intensified those concerns.
The U.S. military struck five Iranian tankers after attempted missile attacks on a U.S. Navy warship, while Iran said it attacked multiple ships. Iran-backed Houthi forces have also targeted energy infrastructure in Saudi Arabia and expanded pressure around Red Sea shipping routes.
Those developments helped push Brent from below $80 in early August to more than $107 Thursday, an increase of more than 30% in roughly a month.
Vance Has Been More Cautious About a Timeline
Vice President JD Vance has been less willing to attach a date to the conflict’s end.
Asked last week whether the war could finish before the midterms, Vance said he did not want to establish “artificial timelines” and acknowledged that he could not predict when Iran would stop attacking ships.
That position differs from Trump’s expectation that the conflict will end shortly after the election, though both officials have emphasized uncertainty surrounding Iran’s next actions.
From a financial-market perspective, that uncertainty matters more than the calendar.
A ceasefire or sustained reopening of major Middle Eastern export routes could quickly reduce the geopolitical premium embedded in oil prices.
Continued tanker attacks, refinery disruptions or additional restrictions around Hormuz could keep crude elevated or push it higher.
Gasoline Is Already More Than $1 Above Last Year
The increase at U.S. filling stations has become substantial.
AAA’s September 10 national average of $4.277 for regular gasoline is roughly $1.08 higher than a year earlier, when drivers were paying about $3.19.
Diesel has experienced an even larger increase, climbing from approximately $3.71 a year ago to a record $5.98.
California motorists are paying some of the highest prices in the country, with regular gasoline around $5.90 and diesel near $7.91. California regular gasoline is about $1.27 above its year-ago level, while diesel has increased by roughly $2.76.
The economic effect extends well beyond what households pay when they fill their cars.
Diesel is heavily used in trucking, construction, agriculture and manufacturing. When diesel becomes more expensive, companies can either absorb the increase through lower margins or attempt to pass it along through higher freight charges and product prices.
Jet fuel is creating similar pressure for airlines.
Carriers have already cut some flights, increased fares and raised fees as higher fuel expenses squeeze operating economics. JetBlue, for example, increased its expected third-quarter fuel price Thursday to $3.96 per gallon from $3.49 while simultaneously reducing its capacity-growth forecast.
Ryanair CEO Michael O’Leary also warned that airfares could rise materially if elevated oil prices persist into 2027.
The Inflation Impact Is Already Showing Up
Thursday’s U.S. producer-price report offered evidence that higher energy costs are filtering deeper into the economy.
The Producer Price Index rose 0.4% in August and 5.4% from a year earlier, accelerating from a 4.8% annual increase in July.
Diesel prices at the producer level jumped 24.1% in August alone and were 78% higher than a year earlier. Core producer prices, excluding food and energy, increased 0.2% for the month and 4.6% from a year ago.
Those figures largely predate the latest jump in crude above $100.
That creates an important timing issue for investors.
August inflation data capture some of the energy shock, but Thursday’s Brent move above $107 and diesel’s new record will affect economic activity after the period measured by the latest PPI report.
If energy prices stay elevated through September, businesses could face another month of higher transportation, manufacturing and distribution expenses.
How much eventually reaches consumers will depend on pricing power.
Large retailers, manufacturers and transportation companies may absorb some costs temporarily. Others may use surcharges or price increases to protect margins.
That is why oil can influence inflation even when consumers are not directly purchasing petroleum products.
Higher transportation expenses can eventually become part of the price of groceries, apparel, building materials and other goods.
The Fed Now Has Another Reason to Watch Energy Closely
The surge is occurring immediately before the Federal Reserve’s September 15-16 policy meeting.
The central bank is already dealing with inflation above its 2% target. Persistent increases in energy and transportation costs could make it harder for policymakers to become confident that price pressures are moving sustainably lower.
Friday’s August Consumer Price Index will provide another important reading before the meeting.
Fed officials do not generally respond mechanically to temporary oil shocks. Monetary policy cannot produce additional crude or reopen shipping lanes.
The risk comes when higher energy prices begin influencing a broader range of prices or inflation expectations.
If businesses repeatedly pass higher fuel costs to customers, or workers and consumers begin expecting elevated inflation to persist, policymakers may view the shock as more than temporary.
Higher interest rates would create another financial consequence from the same geopolitical event.
Treasury yields are already near multiyear highs, with the 10-year yield approaching 5% as investors respond to inflation, fiscal concerns and uncertainty surrounding monetary policy.
That combination — $100-plus oil and elevated long-term interest rates — can pressure housing, consumer credit, corporate borrowing and equity valuations simultaneously.
Energy Producers and Fuel-Intensive Companies Face Opposite Effects
For stocks, the oil rally creates a clear split between beneficiaries and companies facing higher operating costs.
Large producers such as Exxon Mobil, Chevron, ConocoPhillips and Occidental Petroleum could benefit from stronger realized crude prices if production remains stable.
Higher commodity prices can increase revenue and operating cash flow relatively quickly because much of a producer’s cost base does not rise at the same rate as the selling price of oil.
Refiners can also benefit when shortages of gasoline or diesel cause refining margins to widen.
The other side of the trade includes airlines, trucking companies, delivery businesses, manufacturers and consumer companies exposed to freight.
Fuel costs can reduce margins unless companies successfully pass them through.
Households are exposed as well.
A driver purchasing 50 gallons of gasoline a month would spend roughly $54 more at today’s national average than at the year-ago price, before accounting for any indirect increase in food, transportation or travel costs.
Individually, that may not transform household finances. Across millions of consumers, sustained energy inflation can redirect billions of dollars away from discretionary categories.
That is one reason retailers and restaurants may watch gasoline prices closely going into the holiday season.
The Strategic Petroleum Reserve Has Less Cushion
The federal government has attempted to soften the energy shock through releases from the Strategic Petroleum Reserve.
But those withdrawals have significantly reduced the amount of crude remaining in the emergency stockpile.
SPR inventories fell to approximately 285.4 million barrels in early September, the lowest level since November 1982. The reserve has declined by more than 100 million barrels since the beginning of 2026 as part of a broader agreement to release 172 million barrels.
That does not mean the government cannot release additional barrels.
It does mean the reserve now contains considerably less oil than it did before the conflict intensified.
Domestic production offers another source of supply.
U.S. crude output recently reached a record 13.9 million barrels per day, while commercial crude inventories stood at roughly 424 million barrels.
Record American production has helped cushion the market but has not been enough to fully offset disrupted Middle Eastern exports and declining global inventories.
EIA Sees Oil Staying Elevated Into 2027
The government’s own energy forecast does not assume an immediate return to prewar conditions.
The Energy Information Administration’s September Short-Term Energy Outlook estimates that global oil inventories have fallen by approximately 400 million barrels so far in 2026.
EIA expects inventories to keep declining through year-end and assumes some constraints on Middle Eastern exports will persist until the second quarter of 2027.
Its baseline forecast, completed September 3 before the latest escalation, called for Brent crude to average roughly $90 a barrel during the second half of 2026. The agency forecasts an average Brent price of $91 for the full year, compared with $69 in 2025.
Thursday’s price above $107 is therefore well above EIA’s second-half baseline.
EIA also forecast an average U.S. retail gasoline price of $3.84 for 2026 and $3.35 in 2027. AAA’s current $4.277 national average is already considerably higher than that full-year estimate.
The forecast could still prove accurate if crude prices retreat during the remainder of the year.
But the gap shows how quickly the outlook has changed since EIA completed its projections on September 3.
Trump’s Post-Election Forecast Depends on the War, Not the Election Itself
Trump’s expectation that oil will fall after November 3 ultimately depends on his broader forecast that the conflict with Iran will ease after the election.
The election date itself does not alter global petroleum supply.
If Iran and the United States reduce hostilities, tanker traffic normalizes and production returns, crude prices could decline regardless of the political calendar.
If disruptions remain severe, oil could stay elevated after voting ends.
Trump has also said gasoline could fall below $2 a gallon after the conflict is resolved. That would require a very large decline from the current national average of $4.277 and would likely depend on a substantial reduction in crude prices and refining costs.
There is no current EIA forecast for sub-$2 gasoline. The agency’s latest national projection averages $3.35 a gallon in 2027.
That difference makes the distinction between a political forecast and an official energy-market forecast particularly relevant.
Investors do not need to decide which prediction will ultimately prove correct today.
They can watch the variables that would have to move first.
Hormuz shipping volumes, Middle Eastern production, Brent crude, U.S. inventories and refinery margins will offer earlier evidence of whether fuel-price relief is becoming more likely.
The Next Few Days Matter Before November Does
The immediate catalysts arrive long before the midterm elections.
Friday’s Consumer Price Index will show how much inflation pressure was present in August, while the Federal Reserve will announce its next interest-rate decision on September 16.
Oil markets will continue reacting to developments around Iran, tanker traffic and Saudi energy infrastructure on a daily basis.
EIA’s next Short-Term Energy Outlook arrives October 6, giving the agency its first opportunity to fully incorporate September’s latest escalation into its official forecasts.
For households, the simplest measure will remain the number posted at filling stations.
Gasoline is now more than a dollar above its year-ago level nationally. Diesel is at a record. Brent has surged above $107, substantially above the government’s latest baseline forecast.
Trump says those pressures will begin reversing after the November election because he expects the Iran conflict to wind down.
The market will provide evidence much sooner: if crude shipments recover and Brent starts retreating, gasoline could begin following it lower. If disruptions deepen and oil remains above $100, consumers, companies and the Federal Reserve may have to contend with elevated energy costs well beyond Election Day.